UPI MDR has a blind spot – mid-sized businesses
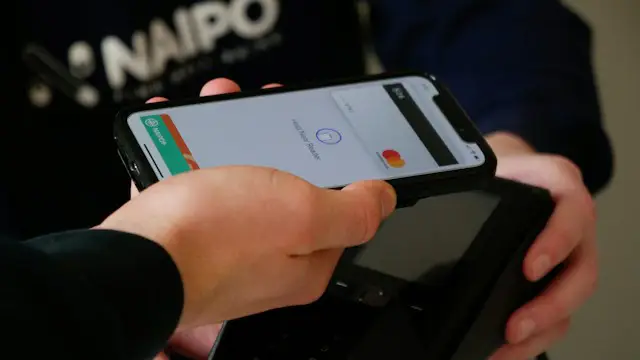
From October 15th, when a neighbourhood chemist anywhere in India accepts a Rs 5,000 payment through the Unified Payments Interface (UPI) for a customer’s monthly medicines, Rs 20 of it – a full 0.4% – goes to the bank as a UPI fee. Under the new UPI merchant discount rate, a business that receives Rs 500,000 through UPI pays only Rs 300, or 0.06%. In proportion to what they receive, the small chemist pays almost seven times as much as the larger business.
Charging a UPI fee is fair and arguably long overdue. Running the system is expensive, and it cannot rely on government subsidies forever. But the way the UPI fee has been designed gets fairness exactly backwards. Big-ticket transactions end up paying the smallest share, while the heaviest burden lands on mid-sized businesses and small traders, the people who can least afford it. A fee meant to make UPI sustainable could end up burdening the very merchants and businesses that made it successful.
How the UPI fee works
The rules are straightforward. From October 15th 2026, merchants will pay a UPI fee of 0.4% on UPI payments over Rs 2,000. The charge is called the Merchant Discount Rate (MDR), so a Rs 20,000 sale costs the merchant Rs 80. The charge was introduced under the Payment and Settlement Systems Act, was shaped by the deliberations of the UPI Steering Committee and applies across the country.
Customers pay nothing extra, and merchants cannot pass the UPI fee on to them. Transfers between individuals remain free. Small merchants who receive up to Rs 100,000 a month through UPI QR codes are fully exempted. The UPI fee is capped at Rs 300 for any single transaction, a ceiling the 0.4% rate reaches at Rs 75,000. Any payment above that amount is charged the same Rs 300.
Importantly, this UPI fee is not a tax, and the money does not go to the government. It goes to the banks and payment apps that process each payment: the customer’s bank, the merchant’s bank and apps such as Google Pay and PhonePe.
Why the UPI fee has a case behind it
The UPI fee has solid justification. UPI handled transactions worth Rs 314.23 trillion last financial year, and each one depended on banks and payment apps to maintain servers, check for fraud, and resolve complaints. Since 2020, banks and payment apps have not been allowed to charge merchants for UPI payments, so the government has had to cover part of the cost. This year’s budget allocates Rs 20bn for that subsidy, funded by all taxpayers, even those who rarely use UPI. The government has said that this support was always meant to be a temporary bridge, not a lasting solution. And even at 0.4%, UPI remains far cheaper for merchants than card payments, which usually cost 1% to 2%.
Where the UPI merchant discount rate gets fairness backwards
The issue isn’t the UPI fee itself, but how it’s structured. Up to Rs 75,000, every merchant pays the full 0.4%. Above that, the Rs 300 cap steadily pulls the effective rate down: to 0.3% on a Rs 100,000 payment, to just 0.15% on a Rs 200,000 payment and to 0.06% on Rs 500,000. In other words, the bigger the transaction, the lower the share charged.
This might be harmless if the burden fell evenly, but it does not. At a local chemist, a small electronics shop or a corner shop, most sales fall between Rs 2,000 and Rs 75,000, so these businesses pay the full rate on almost every transaction. The worst affected are those just above the Rs 100k-a-month exemption: too big to avoid the UPI fee, but far too small to benefit from the cap. Many of them operate on slim margins, where losing 0.4% on every sale is not a rounding error. Meanwhile, businesses handling large payments, which are usually better able to absorb costs, pay the least in proportion. A UPI fee designed to be fair ends up demanding the most from those who can least afford it.
The risk of pushing small merchants back to cash
Fairness is not the only concern. Merchants cannot add the UPI fee to the customer’s bill, but nothing stops them from quietly raising prices, so consumers will end up bearing the cost one way or another. More worryingly, small businesses are not obliged to accept UPI at all. A shopkeeper losing 0.4% on every digital sale has every reason to steer customers back to cash, perhaps with a small discount. Every such sale removes another transaction from the formal economy and sets back the digital India the government has spent a decade building. It would be deeply ironic if the very shopkeepers who turned UPI into a national success became the first to turn away from it.
Three changes to make the UPI fee fairer
None of this means that the UPI fee should be scrapped. It means the UPI fee should be redesigned, and three straightforward changes would make it fairer.
First, a tiered rate: 0.2% on payments between Rs 2,000 and Rs 20,000, the range that covers most everyday purchases at small shops, and 0.4% on anything higher. Second, a higher cap. Raising the limit from Rs 300 to around Rs 1,000 would ensure that the largest payments pay their fair share rather than the smallest ones. Third, a gradual rollout, with rates reaching these levels over two years instead of all at once, would give merchants time to adjust prices and margins.
Together, these changes would keep UPI financially viable, as the revenue lost on smaller payments would be recovered from larger ones. Crucially, they would spread the burden according to who can bear it, not according to who happens to deal in small markets.
Getting the fairness right
Go back to the neighbourhood chemist, giving up Rs 20 on a Rs 5,000 sale while a much bigger business pays only a fraction of that share. No one is demanding that UPI stay free forever; the system has earned the right to cover its own costs. But a UPI fee that takes the most from those who can least afford it does not move UPI towards sustainability. It moves away from the very people who made UPI successful. India got the technology right. Now it must get the fairness right too.

Arjun Singh is a student interested in finance, economics and financial markets. He wrote this article with guidance from Rishabh Sethi, a professor at the University of Petroleum and Energy Studies (UPES), whose mentorship helped refine its financial and analytical perspective.