Turning Asia’s economic growth into prosperity
Asia is increasingly consolidating its position as one of the world’s centres of economic growth. Behind its relatively high figures, however, the region faces a fundamental question: is Asia’s economic growth genuinely improving people’s purchasing power, strengthening savings and reducing household vulnerability? High growth does not necessarily translate into prosperity if its benefits are concentrated in certain sectors while living costs and debt burdens continue to rise.
In its October 2026 World Economic Outlook (WEO), the International Monetary Fund (IMF) projects growth in Asia and the Pacific to slow from 5% in 2025 to 4.8% in 2026 and 4.4% in 2027. Although economic growth remains higher than in many other regions, the trend indicates that Asia is not entirely immune to global shocks.
The IMF projects India to grow by 7% in 2026, while China is expected to grow by around 4.5% and Indonesia by approximately 5.1%. These differences show that Asia is not a homogeneous economic entity. Industrial structures, technological capabilities, demographic conditions and the strength of domestic consumption determine how effectively each country can capitalise on opportunities for economic growth.
IMF Real GDP Growth Projections
Asia’s economic growth and its structural challenges
One of Asia’s strengths is the integration of manufacturing, trade, and technology. Global demand for artificial intelligence (AI) devices, semiconductors, data centres, and electronic products is boosting several countries connected to technology supply chains. India is also benefiting from its large domestic market and the expansion of its services sector.
However, dependence on exports and external demand can become a weakness when global trade slows. West Asia conflicts, rising energy prices, tariff uncertainty, and shifts in capital flows can raise production costs and weigh on investment. In its Regional Economic Outlook for Asia and the Pacific, the IMF warns that rising energy prices could fuel inflation, widen trade deficits and narrow the fiscal space of energy-importing countries.
In Solow’s growth theory, capital, labour and productivity growth determine long-term production capacity. Economic growth driven solely by exports or investment expansion is therefore insufficient. Asia must ensure that technology raises productivity broadly, including in small businesses, agriculture and domestic services.
Does economic growth improve prosperity?
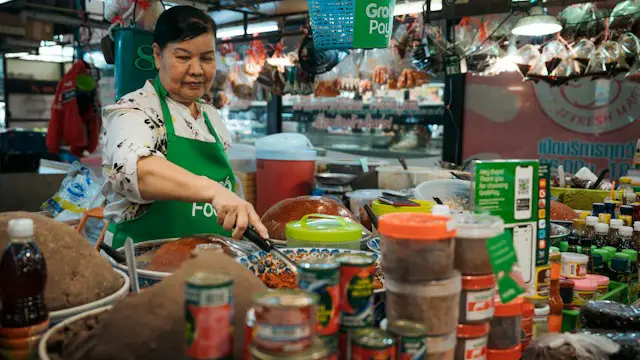
The impact of economic growth on society must be assessed through inflation, household debt, consumer confidence, retail sales, savings and purchasing power. No single indicator represents all of Asia, so the analysis must distinguish between conditions in individual countries.
China provides an important example. According to the Asian Development Bank, China’s retail sales fell by 0.6% year on year in May 2026. Weak income expectations, problems in the property sector and low consumer confidence have become obstacles to domestic consumption. Substantial production capacity, in other words, does not automatically guarantee strong household demand.
In Keynesian theory, consumption is an important component of aggregate demand. When households worry about future income, they tend to postpone purchases and spend more cautiously. Businesses then face weaker sales, reducing their incentive to expand production and hire workers.
Conversely, rising food and energy prices can reduce real income, particularly for low-income groups that spend a large share of their budgets on basic necessities. If households use their savings or take on additional loans to maintain consumption, their ability to withstand subsequent shocks becomes increasingly limited.
Asian governments therefore need to judge economic success not only by gross domestic product (GDP) growth, but also by changes in real wages, per-person consumption, household debt ratios, savings and consumer confidence.
How Asia compares with Africa, Americas and Europe
The October 2026 WEO projections reveal differences in the sources of economic growth across regions. Asia and the Pacific are expected to grow by 4.7% under the IMF’s regional classification in the comparative table, while Africa is projected to grow by around 4.6%, North America by 2.2%, Latin America and the Caribbean by 2.3% and Europe by 1.3%. Differences in regional figures can arise from the country coverage used for each group.
IMF Projected Economic Growth by Region
Asia is supported by manufacturing, technology, services and growing domestic demand. Africa benefits from several high-growth economies but still faces constraints in infrastructure, financing, and production diversification. North America benefits from technology and AI investment, while Latin America faces challenges related to productivity, commodity dependence and uneven investment. Europe faces problems involving productivity, demographics, energy costs and market fragmentation.
The comparison shows that economic growth is not simply a matter of the size of the numbers. Economic structure and the ability to turn investment into productivity determine how sustainable an expansion is.
Next agenda for Asia’s economic growth
Asia needs to pursue four measures. First, it must broaden its sources of economic growth by strengthening domestic consumption, raising real wages in line with productivity and providing well-targeted social protection. Second, it must accelerate technological transformation so that the benefits of AI and digitalisation are not enjoyed only by large companies and certain countries. Third, it must safeguard fiscal sustainability and financial stability by managing debt risks, strengthening government revenue and avoiding broad subsidies that burden budgets over the long term. Fourth, it must deepen regional integration through trade, investment, energy and cross-border supply chains.
Asia still has substantial opportunities to become a global engine of economic growth. The next challenge, however, is not merely to keep economic growth above the global average. The real challenge is to ensure that this growth raises real incomes, strengthens purchasing power, expands employment opportunities and builds household resilience. After all, successful economic growth is not merely growth recorded in national statistics, but growth that people genuinely feel in their daily lives.

Eko Setiobudi, SE, ME, is an economist, lecturer at STIES Mitra Karya Bekasi, Indonesia, and business practitioner. His areas of interest include macroeconomics, fiscal policy, financial markets, economic development, international trade, and Indonesia’s role in the global economy. He writes commentary and analysis on Indonesia, ASEAN, Asia, and global economic affairs.